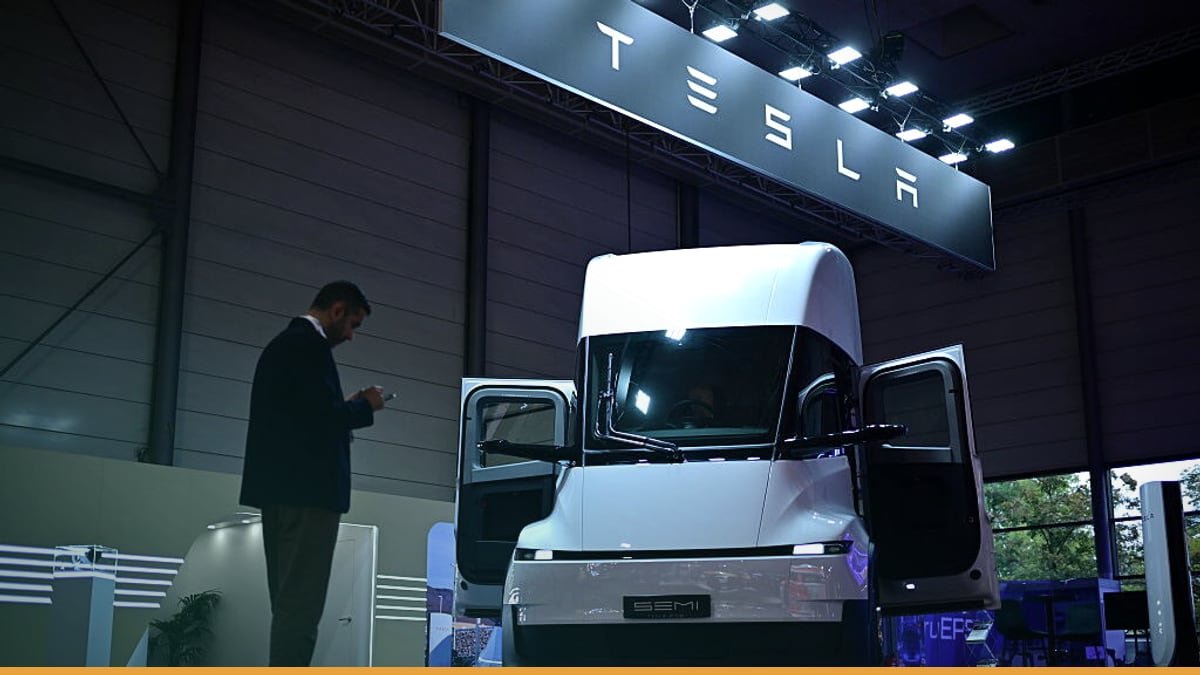
Header image source: Tesla’s Big Electric Truck Faces An Even Bigger Infrastructure Challenge – Vignana Varadhi via Vignana Varadhi via Google — cropped to 16:9 and colour-adjusted.
Key takeaways
- Tesla’s Semi offers 500-mile range but needs charging infrastructure that doesn’t exist in the US
- Most US truck stops lack megawatt chargers needed for heavy-duty EVs
- Fleet managers face trade-offs between range, charging time, and grid capacity
Tesla just rolled the first production Semi trucks off the line in Sparks, Nevada. 500-mile range. Unique driver positioning. Elon Musk called it “really a driver’s truck.” After seven years of vapourware, the electric big rig is finally real. But the truck can go the distance. The charging network it needs to refuel doesn’t.
Not in the U.S., anyway.
That 500-mile number is the headline. It’s the first heavy-duty EV to crack the psychological barrier that separates regional hauls from true long-haul trucking. Competitors like Freightliner’s eCascadia and Volvo’s VNR Electric offer significantly less range than Tesla’s Semi. Rivian’s Amazon vans offer substantially less range. Tesla’s range advantage isn’t incremental. It’s a step change.
But range is only half the equation.
The other half is where and how you recharge. On that front, Tesla is starting from zero.
The Semi’s Long Road to Production: A Decade of Delays and Deliveries
Tesla unveiled the Semi concept years ago with production targets that were repeatedly delayed. That didn’t happen. Production was repeatedly delayed over multiple years. Last week’s Nevada event marked the first official delivery of production Semis—nearly a decade after the concept.
For context, competitors have been delivering electric trucks for several years. Volvo’s VNR Electric has been available for several years. Rivian’s EDV vans have been in operation for several years. Tesla is late to a market its competitors have been quietly shaping.
Why the delay? Battery density, for one. Tesla needed a pack that could deliver 500 miles without turning the Semi into a rolling brick. The company hasn’t disclosed the specific battery chemistry or architecture. Weight is still a trade-off—the battery pack adds significant weight compared to diesel systems.
That eats into payload.
Tesla is betting the range advantage offsets the weight penalty for fleets that can’t afford to stop every 200 miles.
Then there’s the driver experience. Musk’s “driver’s truck” comment isn’t just marketing fluff. The Semi ditches the traditional cab layout for a central seating position, a wraparound dashboard, and a low step-in height. It’s a radical departure from the ergonomics of a Freightliner or Peterbilt, where the driver sits over the engine like a jockey on a horse.
Tesla’s design prioritises visibility and comfort. Features that matter more to drivers than to fleet managers. Whether that’s enough to win over a workforce sceptical of electric trucks remains to be seen.
The 500-Mile Range Breakthrough: Does It Actually Solve the Problem?
500 miles is the magic number. It represents a typical daily range for long-haul trucking.S. Diesel tractors typically have substantial range, putting Tesla’s Semi in a competitive position.
But range isn’t the same as range anxiety.
With diesel, you pull into a truck stop, fuel up in 10 minutes, and you’re back on the road. With the Semi, charging stops will take significantly longer than diesel refueling. That’s assuming the charger exists. That the grid can handle it. That there’s no queue.
Tesla hasn’t released official certified range figures. Real-world performance will depend on payload, terrain, and weather. Cold weather can significantly reduce EV range. Heavy loads on mountain grades will sap energy faster than flat highway cruising. A fully loaded Semi hauling heavy loads up steep grades could see its range significantly reduced.
Still better than competitors.
But it means route planning becomes a science. Fleets will need to map charging stops like airlines map fuel stops—except the “fuel” isn’t universally available.
Even with 500 miles, long-haul routes will require mid-journey charging. A cross-country trip covering thousands of miles would require multiple charging stops. That would require multiple charging stops. Diesel would require fewer refueling stops. The Semi’s range advantage shrinks when you factor in charging time.
And that’s before you account for the fact that most truck stops don’t have 1 MW chargers. Or any chargers at all.
The U.S. Charging Desert: Why Truck Stops Aren’t Ready
The U.S. has a limited number of public DC fast chargers. Very few chargers are capable of delivering the high power levels needed for heavy-duty trucks. Most passenger-car chargers lack the power capacity needed for heavy-duty truck charging.
Some truck stops have started adding EV chargers. But they’re mostly lower-power units designed for light-duty vehicles. Retrofitting a truck stop for megawatt-scale charging isn’t as simple as bolting on a bigger charger. It requires new transformers, substations, and grid connections—projects that can take years and cost millions per location.
Compare that to China. Electric trucks account for nearly 30% of heavy-duty sales. The country has built out a network of high-power charging hubs along major freight corridors, often co-located with battery-swapping stations. Other markets have made more progress with electric truck adoption. Some European countries are advancing truck-specific infrastructure.
The U.S. is playing catch-up.
The gap isn’t just about technology. It’s about policy, grid capacity, and land availability.
Tesla’s own Megacharger network is a start. But it’s tiny. As of last week, there are fewer than 10 known Megacharger locations in the U.S., mostly clustered around Tesla’s factories and key freight routes in California and Texas. That’s enough for a handful of fleets to run dedicated lanes. Nowhere near the coverage needed for nationwide adoption.
The company has been quiet about expansion plans. The math is brutal. To match the density of diesel truck stops, Tesla would need thousands of Megachargers. Not dozens.
The Fleet Manager’s Dilemma: Cost vs. Convenience
Tesla is pitching the Semi to cost-conscious fleet managers. The economics are more complicated than the sticker price.
Tesla hasn’t disclosed pricing details for the Semi. Industry estimates suggest the Semi carries a premium over comparable diesel trucks. Fuel savings help close the gap. Electricity is cheaper than diesel on a per-mile basis, especially if fleets charge during off-peak hours.
Tesla claims the Semi can deliver substantial fuel savings over time. But that assumes access to cheap, reliable charging.
Maintenance savings are another selling point. Electric trucks have fewer moving parts—no engine, transmission, or exhaust system—so maintenance costs should be lower. But battery degradation is the wild card. Tesla hasn’t released data on the Semi’s battery lifespan. Heavy-duty cycles and fast charging will accelerate wear.
A degraded battery means reduced range. More frequent charging stops.
For fleets operating on tight margins, that’s a risk.
Then there’s the hidden cost of charging downtime. Charging the Semi takes significantly longer than diesel refueling. That’s time the truck isn’t earning revenue. Diesel refueling is much faster than electric charging. Over a year, those extra minutes add up. Fleets could lose significant uptime due to longer charging times, potentially offsetting some fuel savings.
Route planning is the final hurdle. Fleets can’t rely on Tesla’s Megachargers alone. Third-party networks aren’t ready for heavy-duty EVs. That means either building their own charging depots—a capital-intensive proposition—or sticking to routes where charging is available.
For now, the Semi is a regional play. Not a national one.
The Grid Problem: Can the U.S. Handle Megawatt-Scale Charging?
The U.S. grid isn’t ready for the Semi.
A single high-power charger draws enormous amounts of electricity. A truck stop with multiple high-power chargers would require massive grid capacity. Most local grids aren’t built for that kind of load, especially in rural areas where truck stops are located. Upgrading grid infrastructure for megawatt-scale charging requires substantial time and investment.
Demand charges are another headache. Utilities often charge commercial customers based on their peak power draw, not just total energy consumed. A fleet that charges a Semi for 30 minutes at 1 MW could face demand charges that dwarf the cost of the electricity itself. Battery-buffered charging—where a stationary battery stores energy and discharges it to the truck—can help smooth out demand.
But it adds cost and complexity.
The U.S. Infrastructure Bill allocated funding for EV charging infrastructure. Most of that money is earmarked for light-duty vehicles. Truck-specific funding is limited. Federal standards for megawatt-scale charging don’t exist. Without policy support, the burden falls on Tesla and fleets to build the network themselves.
Other markets have different approaches to infrastructure development. The government coordinates grid upgrades, charging infrastructure, and vehicle adoption in a way that’s impossible in the U.S.’s fragmented system. Europe has a head start too. Some European countries are developing truck-specific charging infrastructure.
The U.S. is stuck in a chicken-and-egg loop. Fleets won’t buy trucks without chargers. No one will build chargers without trucks.
Tesla’s Catch-22: Build the Chargers or Lose the Market
Tesla has three options. None of them perfect.
Option 1: Partner with truck stops. Existing truck stop operators have the real estate and customer base. But they lack the grid capacity and the incentive to invest in megawatt-scale charging. Tesla would need to subsidise the infrastructure. Even then, deployment would be slow. Building Megachargers has been a slow process. Scaling to widespread coverage would take many years.
Option 2: Build proprietary charging hubs. Tesla has the capital and the vertical integration to pull this off. But it’s a massive undertaking. Each charging hub represents a major capital investment. And Tesla would be competing with its own customers. Why would a fleet buy a Semi if Tesla’s chargers are the only game in town?
Option 3: Rely on third-party networks. Third-party charging networks are expanding. But their chargers aren’t designed for heavy-duty trucks. Upgrading them to 1 MW would require new hardware, new software, and new grid connections.
It’s possible. But it’s not happening fast.
The risk is clear. If Tesla doesn’t solve the charging problem, fleets won’t buy Semis. The 500-mile range is impressive. But it’s useless without a place to plug in. Rivian and Freightliner have already secured early adopters in regional hauling. Tesla is playing catch-up.
The clock is ticking.
The Competitive Landscape: Who’s Already Ahead?
Tesla isn’t the only player in electric trucking. Its late entry could be a liability.
Competitors already have electric delivery vehicles in operation. The company is expanding into medium-duty trucks. Freightliner’s eCascadia has been deployed in real-world fleets for several years. Volvo’s VNR Electric is gaining traction in drayage and regional hauling.
The difference is focus.
Competitors are focusing on shorter-range applications. Tesla is going after long-haul, where 500 miles is the minimum viable product. That’s a riskier bet. But it’s also a bigger market. If Tesla can make the Semi work, it could dominate the segment. If it can’t, it’ll be relegated to niche routes with dedicated charging.
The late entry might also be a feature, not a bug. Tesla has watched its competitors make mistakes—battery range, charging infrastructure, fleet adoption—and it’s had time to iterate. The Semi’s 500-mile range and central driver’s seat are examples of that learning.
But time isn’t infinite. Rivian and Freightliner are already scaling. Legacy truck manufacturers are developing their own electric offerings.
The Policy Wildcard: Will Government Intervention Tip the Scales?
The U.S. Infrastructure Bill’s $7. The funding allocated for EV charging represents only a portion of what’s needed for trucking. Most of that money is going toward light-duty chargers, not the megawatt-scale infrastructure the Semi needs. Truck-specific funding is limited. Federal standards for high-power charging don’t exist.
Without policy support, the burden falls on Tesla and fleets to build the network themselves.
State-level incentives could help. Some states have regulations pushing fleets toward zero-emission trucks. The state has earmarked funding for truck charging. But California is an outlier. In red states, resistance to EV mandates could slow adoption. Future emissions regulations could accelerate the transition to electric trucks.
But infrastructure delays could push back compliance deadlines.
The wildcard is China. The country’s electric truck adoption is a preview of what’s possible with coordinated policy, grid investment, and infrastructure buildout. If the U.S. doesn’t close the gap, American fleets could find themselves at a competitive disadvantage—stuck with diesel while Chinese and European truckers go electric.
The Bottom Line: Is the Tesla Semi a Revolution or a Niche Play?
The Semi’s specs are impressive. 500-mile range. Central driver’s seat. Potential for massive fuel savings.
But specs don’t move trucks.
Infrastructure does.
Right now, the U.S. charging network is missing the high-voltage backbone that heavy-duty EVs need. Tesla’s Megacharger network is a start. But it’s not enough. Not even close.
The best-case scenario: Tesla partners with truck stops, grid upgrades happen, and the Semi becomes the default for long-haul trucking.
The worst-case scenario: charging gaps persist, fleets stick with diesel, and the Semi becomes a regional niche product—another Tesla moonshot that never quite lands.
Early adoption will be limited to routes with Tesla Megachargers—California, Texas, maybe the Northeast. Broader rollout depends on whether Tesla can scale its charging network. Or whether third-party players step up.
Either way, the Semi’s success hinges on infrastructure.
Not engineering.
And on that front, the grid isn’t ready.